Heidi Raises $340M as Clinical AI Valuation Hits $900M
– 4 min read
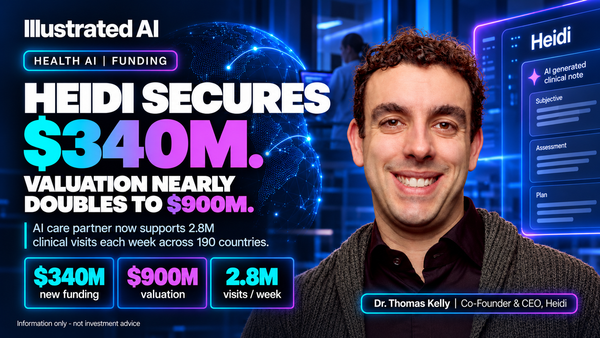
Heidi has raised $100 million in a Series C equity round led by Blackbird, valuing the clinical-AI company at $900 million. Existing investors Phoenix Court, Point72 Private Investments and Headline also participated.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
Alongside the equity round, Heidi secured a separate $240 million non-dilutive growth investment led by General Catalyst’s Customer Value Fund. This brings the announced financing package to $340 million, but only the $100 million Series C is an equity round. Heidi has not disclosed the cost, deployment schedule or other detailed economics of the growth financing.
Heidi was founded in 2019 as Oscer, initially focusing on medical education, before moving into clinical documentation. It now describes its broader platform as an “AI Care Partner”. The company is expanding into tools intended to support clinicians before, during and after consultations. Whether this produces durable commercial value will depend on product adoption, clinical reliability, customer retention and the economics of expanding beyond documentation.
Blackbird led Heidi’s $100 million Series C, which established the reported $900 million valuation. The separate $240 million investment from General Catalyst’s Customer Value Fund is non-dilutive growth financing intended to support go-to-market expansion.
Non-dilutive financing avoids issuing additional equity, but it should not be treated as cost-free capital. Heidi has not disclosed the return structure, repayment economics, conditions for drawing the full amount or how quickly the financing will be deployed.
The structure gives Heidi additional resources for customer acquisition and expansion while limiting immediate shareholder dilution. Its ultimate value will depend on whether the resulting customer revenue exceeds the cost of that financing.
Heidi says its annual recurring revenue increased from approximately $1 million to $50 million over two years, reaching the latter figure in April 2026. The company has not publicly disclosed recognised revenue, gross margins, profitability, net revenue retention or customer concentration.
Heidi also reports supporting approximately 2.8 million patient interactions per week across more than 190 countries and 110 languages, with more than 175 million cumulative patient visits. These figures demonstrate broad product usage, but they do not reveal how many interactions are generated by paying customers, free users or institutional contracts.
Heidi’s reported valuation increased from $465 million following its October 2025 Series B to $900 million in the latest equity round. The valuation reflects negotiated investor expectations; it does not independently validate clinical performance or sustainable financial results.
Healthcare documentation requires more than transcription accuracy. Clinical-AI systems must handle different accents, specialties, terminology and consultation formats while preserving relevant information and avoiding unsupported additions.
Heidi’s broader “Care Partner” strategy introduces further questions about clinician oversight and responsibility. Tools that prepare information, surface research or assist with follow-up may carry different risks from software that drafts notes. Heidi must demonstrate how outputs are reviewed, how errors are identified and how patient data is protected across jurisdictions.
Investors should examine independently assessed accuracy, correction rates, safety incidents, data-residency controls and the amount of clinician review required. Trust and workflow integration may support retention, but they do not constitute a defensible moat until reflected in renewal and expansion data.
Heidi has secured healthcare-system relationships, including an NHS Midlands clinical-documentation procurement covering 15 acute and community trusts and integrated care boards, as well as 1,239 GP practices. It also identifies private-sector customers including PortmanDentex and Sue Ryder.
These relationships provide evidence of institutional adoption, but Heidi has not disclosed contract values, implementation volumes, renewal rates or the revenue contribution from health-system customers. Investors should distinguish framework access and product availability from sustained paid use.
Revenue quality: How much of the reported $50 million ARR comes from individual subscriptions versus enterprise health-system contracts?
Retention and expansion: Do clinicians and institutions renew, add users and adopt products beyond documentation?
Clinical reliability: Relevant evidence includes documentation accuracy, correction rates, omitted information, unsupported output and clinician-review requirements.
Growth-financing economics: Heidi should disclose how the $240 million facility is drawn, its effective cost and the customer performance required to support it.
Margins and cash consumption: Expansion across languages, jurisdictions and enterprise systems may require significant implementation, support, compliance and sales expenditure.
Product adoption beyond notes: The Care Partner strategy will become commercially meaningful only if preparation, research and follow-up tools generate recurring paid usage.
The bottom line: Heidi’s $100 million Series C at a $900 million valuation and separate $240 million non-dilutive growth investment provide substantial resources for product and commercial expansion. Its reported $50 million ARR and 2.8 million weekly patient interactions indicate strong momentum, but these figures remain company-reported and detailed financial disclosure is limited. Investors should watch recognised revenue, retention, gross margins, enterprise contract growth, clinical accuracy and whether products beyond documentation generate sustained paid adoption.