Nscale’s $3.36B Pre-IPO AI Infrastructure Raise
– 4 min read
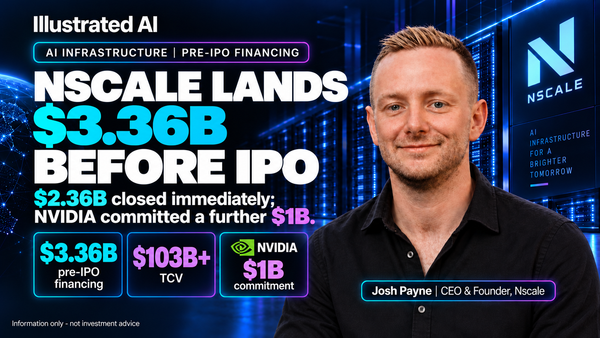
Artificial intelligence is no longer just software magic. Behind every chatbot response and generated image sits an enormous industrial machine requiring electricity, land, cooling systems, advanced chips and purpose-built facilities. Nscale’s $3.36 billion pre-IPO financing makes this shift unmistakable.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
Unlike classic software, AI infrastructure cannot scale cheaply. Every wave of demand requires more hardware, more facilities and more energy. Growth means physically delivering capacity. That is why financing has moved from millions to billions, creating a new class of company blending cloud computing, utilities and software platforms.
Nscale is developing infrastructure spanning power supply, liquid-cooled data centres, GPU clusters and cloud software. The company’s operating footprint combines active infrastructure with facilities and capacity that remain under development. A chip shortage delays expansion. A power shortage leaves chips idle. Weak cooling constrains performance. In AI, the chain is only as strong as its weakest link.
Nscale raised $3.36 billion through convertible loan notes led by Third Point. The financing comprises an initial $2.36 billion tranche at closing and a further $1 billion commitment from NVIDIA, with funding expected in mid-November 2026.
The notes will convert automatically into ordinary shares—or non-voting shares in NVIDIA’s case—if Nscale completes its proposed IPO. However, Nscale has not disclosed the conversion price, interest rate, maturity or resulting shareholder dilution.
The financing follows a $2 billion Series C announced in February 2026 at a $14.6 billion valuation. The latest transaction does not establish a new equity valuation. Nscale has filed for an NYSE listing under the ticker NSCL, but the number of shares, offering price and listing timetable remain undetermined.
Nscale describes its model as vertically integrated across power, data centres, GPU infrastructure and cloud software. This structure could improve coordination and deployment speed, but it also concentrates construction, financing and operational risk within the company. Nscale uses a combination of company-controlled and partner-operated facilities, while substantial future capacity remains under development.
The company has not yet demonstrated that vertical integration will improve margins. Commercial performance will depend on construction schedules, power availability, equipment delivery, utilisation and the cost of operating each facility.
Nscale reported $103.4 billion of active and contracted total contract value as of 31 August 2026. This represents prospective revenue across the terms of signed agreements—not recognised revenue, cash received or a conventional short-term backlog.
Only $2.6 billion, approximately 2.5% of the total, was classified as active. Realising the remaining value depends on Nscale financing, constructing and activating the required infrastructure and then meeting its service obligations.
Long-duration agreements may provide revenue visibility, but investors must examine activation schedules, financing requirements, termination provisions and customer concentration. Contracted demand does not remove the capital or execution required to make that capacity operational.
The financing was led by Third Point and supported by NVIDIA, funds managed by Apollo, Citadel, Hudson Bay Capital, Abu Dhabi Investment Council and 8090 Industries, among other investors. Goldman Sachs acted as placement agent.
Participation from financial institutions, infrastructure investors and a major technology supplier indicates substantial appetite for financing AI capacity. It does not independently validate Nscale’s valuation, profitability or ability to complete its planned deployments.
NVIDIA’s $1 billion commitment is strategically relevant because Nscale’s expansion depends heavily on advanced GPU infrastructure. However, the investment does not guarantee equipment availability, successful project delivery or attractive operating margins. Investors should assess the economic terms, supply arrangements and resulting dilution when further information becomes available.
The use of convertible notes also reflects Nscale’s need to raise capital ahead of its proposed IPO. Without disclosure of the interest rate, conversion price and maturity, investors cannot yet determine the complete cost of this financing.
Nscale reported first-half 2026 revenue of $140.6 million and a net loss of $1.02 billion. The loss included substantial fair-value charges and share-based compensation, but cost of revenue reached $189.6 million and adjusted EBITDA remained negative at approximately $199.2 million.
The company also disclosed approximately $24 billion of technology-equipment commitments and $3.5 billion of data-centre construction and related commitments. The new financing strengthens Nscale’s capital position but does not eliminate the need to fund and complete its planned deployments.
Customer concentration is another material risk. Nscale’s largest customer generated 52% of first-half revenue, while agreements associated with Microsoft and Anthropic represented approximately 85% of disclosed total contract value.
The bottom line: Nscale’s $3.36 billion convertible financing provides substantial additional capital ahead of its proposed IPO, including an initial $2.36 billion tranche and a further $1 billion commitment from NVIDIA expected in November 2026. However, only $2.6 billion of its $103.4 billion contract value was active at the end of August, while the company remains loss-making and faces major equipment, construction and financing commitments. Investors should focus on dilution, capacity activation, customer concentration, gross margins and the conversion of contracted value into recognised revenue.