Go.AI’s $85M Bet on Private, On-Prem AI for Banks
– 4 min read
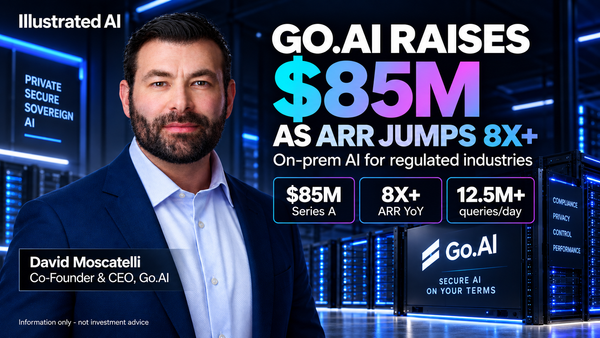
Go.AI has raised $85 million in a Series A round led by Updata Partners, with participation from existing investors GFT Ventures and LAUNCH. The financing brings the company’s total funding to $90 million and will support engineering, product development and commercial expansion.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
Go.AI did not disclose the valuation attached to the financing.
Go.AI develops hardware and software designed to run AI within customers’ controlled environments. Its proposition is aimed initially at regulated and compliance-sensitive sectors, including financial services, healthcare, aerospace, manufacturing and related industries where data control, auditability and governance can affect adoption.
Banks, insurers and healthcare organisations operate under data-protection, security and governance requirements that can restrict how confidential information is processed through external AI services. Go.AI offers its system on a fixed-fee basis rather than charging per token, which may make some usage costs more predictable. Total economics will still depend on hardware, deployment, maintenance, support, upgrades and utilisation.
For regulated organisations, model capability is only one purchasing consideration. Data control, auditability, deployment security, regulatory responsibility and total cost can be equally important. If an on-premises platform becomes embedded in critical workflows, integration requirements and internal approvals may increase switching costs.
Go.AI says annual recurring revenue increased more than eightfold year over year, that it serves more than 200 customers and that it remains profitable. The company also says customer deployments process more than 12.5 million queries per day. These figures are company-reported, and Go.AI has not disclosed its ARR amount, revenue, margins or definition of profitability.
Usage figures also require clarification. Go.AI’s funding announcement cites more than 12.5 million daily queries, while its website displays eight million daily queries. The pages do not provide matching measurement dates or definitions, so the figures should not be used to calculate a confirmed usage-growth rate.
Investors should assess the quality of this reported growth by examining customer expansion, renewal rates, revenue concentration and the amount of recurring software revenue. Rapid growth does not establish durable demand without evidence that customers continue using and expanding their deployments.
Go.AI’s appliance model combines its Go1 hardware with the Go.OS software platform. The company says the system provides local model execution, information indexing, access controls and records of AI activity within the customer’s environment. Packaging these components together could reduce the integration work required compared with assembling a private AI stack from separate suppliers.
A bank may understand risk and customer service in extraordinary detail yet still lack the resources to build a complete AI stack from scratch. The appliance model is designed to address deployment, monitoring, security and auditability within the customer’s environment. Go.AI promotes fully on-premises configurations with no proprietary data sent to third parties, but customers must verify the architecture, controls and regulatory suitability of each deployment.
An appliance deployed within operational infrastructure may become more difficult to replace as customers integrate it with data, workflows and governance processes. This could support retention, although Go.AI has not disclosed renewal rates or evidence that customers face material switching costs. Competitive performance will depend on deployment speed, reliability, integration requirements and total cost.
Go.AI competes with several alternative approaches to deploying enterprise AI. Cloud giants can respond with private cloud options and stronger governance layers. Hardware vendors can bundle AI software around their existing installed base and long-standing customer relationships. Enterprise software incumbents already know where data lives and may simply layer AI capabilities into systems customers already use. Large institutions themselves may choose to build their own stacks entirely.
A specialist provider may compete through integration, deployment speed, governance controls and support. Institutions can also build private AI systems internally, but doing so requires technical resources and coordination across engineering, compliance and legal teams. Go.AI’s commercial advantage will depend on whether its packaged approach reduces that burden at an acceptable cost.
Competitive pressure makes product differentiation and customer retention important measures. Go.AI will need to show that its integrated deployment model produces advantages that customers cannot obtain as easily from cloud providers, hardware vendors or internal development teams. The key question is not whether competition exists. It is whether the product is becoming essential in a way rivals cannot easily replicate.
Big financing rounds open the investment case rather than settle it. Investors will focus on revenue quality: do customers keep spending more, are renewals strong, and do early deployments grow into organisation-wide commitments? Customer concentration is another risk to monitor. A broad customer base indicates healthier, more repeatable demand than dependence on a handful of large accounts.
Margins deserve scrutiny in any business combining hardware and software. Investors need to understand the revenue mix, hardware costs, software margins, installation expenses and continuing support obligations. Go.AI’s reported profitability will become more informative if the company discloses how margins and cash consumption change as hiring and commercial expansion accelerate.
Trust will remain central in regulated industries. Go.AI’s competitive position will depend on system reliability, security controls, auditability, customer support and independently documented deployment outcomes. If customers use the platform for critical production workflows, these capabilities may support stronger retention, although that has not yet been demonstrated through disclosed renewal data.
The bottom line: Go.AI’s $85 million Series A reflects investor interest in on-premises AI infrastructure for regulated organisations. Its reported revenue growth, customer base and query volume indicate commercial momentum, but the figures remain company-reported and lack detailed financial disclosure. Investors should watch disclosed ARR, renewal and expansion rates, customer concentration, deployment costs, hardware margins, software revenue, independently documented customer outcomes and whether profitability continues as the company scales.