Amazon, Decart, and the $7B Bet on AI Infrastructure
– 4 min read
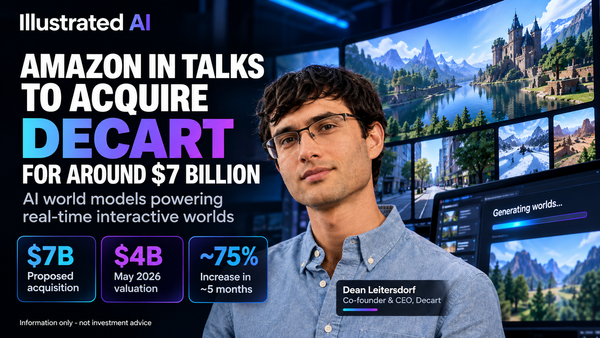
Amazon is reportedly in talks to acquire Decart in a transaction that could value the AI company at around $7 billion, according to The Wall Street Journal, as reported by Reuters on 11 October 2026. No completed agreement has been announced, and negotiations may change or end without a transaction.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
Decart raised $300 million in May 2026 at a reported valuation near $4 billion. The potential acquisition price would be approximately 75% higher, although financing valuations and acquisition prices can reflect different rights, terms and strategic considerations. The reported talks do not independently establish revenue growth, profitability or technical superiority.
In AI, compelling capabilities attract attention, while efficiency can determine commercial viability.
Decart develops Lucy for real-time video generation and transformation, and Oasis for interactive generated environments and physical-AI applications. It also develops DOS, its inference and training optimisation stack. These products address related but distinct workloads.
Interactive world models could support simulation, training and testing. Their usefulness will depend on physical accuracy, consistency over time, controllability and whether results transfer to real-world systems. Visually convincing output alone does not establish a reliable simulator or digital twin.
When AI-generated worlds become tools for testing, training, and planning, they move closer to enterprise budgets and long-term contracts. World models are not merely another AI feature; they are a candidate for an entirely new computing layer.
When AI begins building worlds instead of outputs, the game changes completely.
AI is expensive to run. Inference, using a trained model to deliver real-world outputs, is becoming the persistent cost problem. At scale, those costs can be enormous, turning a popular product into a financial failure. Better optimization means more work with the same hardware, or the same work at lower cost.
Decart describes technology built across NVIDIA GPUs, AWS Trainium and Google TPUs. Supporting several architectures could give customers more hardware options, but portability, performance and migration costs will depend on the model, workload and implementation. This matters because cloud operators want flexibility: the ability to route workloads more intelligently, lower latency, and improve margins. Reducing latency is not a technical luxury; in live interactive AI, delay destroys the experience entirely.
Integration into production workflows could create switching friction, but a durable advantage would require evidence of customer retention, measurable performance gains and competitive operating costs. The AI boom is entering a more mature phase where economics matter as much as astonishment.
In the AI economy, the brightest spotlight is on the demo, but the real treasure sits in the engine room.
The modern AI battle is a contest over the full stack: chips, cloud infrastructure, optimization software, and applications. Cloud providers want to shape the economics of AI itself, not merely collect rent. That means investing in custom silicon and building software layers that keep customers inside their ecosystem.
A custom chip is not enough alone. Developers must run models effectively on it, and workloads must be portable. Software that bridges chip ambition and commercial reality can turn in-house silicon from an interesting option into a genuine platform pillar. Support for multiple chip architectures could expand deployment options. Whether workloads can move economically between them depends on software compatibility, model requirements, capacity availability and migration costs.
An acquisition could strengthen Amazon’s model-development and compute-optimisation capabilities. However, the companies have not disclosed a transaction rationale, integration plan or commitments concerning continued support for competing hardware platforms.
Own more of the stack, and the rules of the market start bending in your favor.
Intense interest is only the beginning of the investment question. Decart faces competitive pressure from cloud providers building optimization tools, chipmakers strengthening software ecosystems, and interactive AI companies racing on quality. Scarcity drives premium valuations, but it should never be confused with certainty.
Five things matter most going forward. First, confirmation: reported talks are not completed deals, and terms, structure, and closing risk all shape true value. Second, openness: whether multi-chip technology remains broadly available or tilts toward one ecosystem will determine its long-term market reach. Third, evidence: claims around latency and inference cost require independent validation, not just compelling demonstrations. Fourth, integration: great technologies can lose momentum inside larger organizations if cultural fit and technical compatibility are underestimated. Fifth, regulation: as AI grows more central to the economy, external scrutiny of combinations affecting cloud power or infrastructure control can reshape timelines and outcomes.
The sharper investor question is simple: does the company make AI better, cheaper, and more strategically powerful for the platform that owns it? The more times the answer is yes, the more the asset is worth.
The bottom line: Amazon’s reported acquisition talks indicate potential strategic interest in Decart’s real-time models and compute-optimisation technology. The approximately $7 billion price remains a reported negotiating figure. Investors should watch whether an agreement is announced, its terms, independent performance comparisons, customer retention and whether deployment efficiencies translate into attractive margins.