Path Robotics Raises $300M to Bring AI Welding to the Factory Floor
– 4 min read
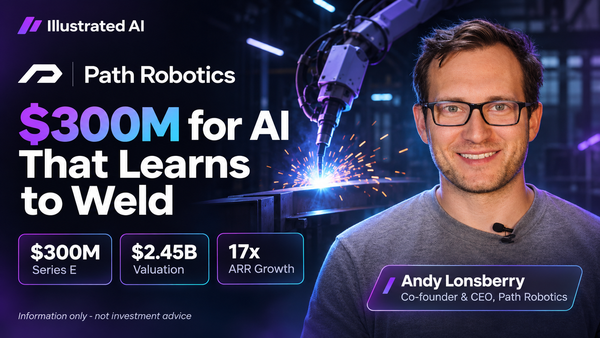
Path Robotics announced a $300 million Series E on 10 November 2026 at a $2.45 billion post-money valuation. Georgian led the round, with participation from existing investors including Addition, Drive Capital, Tiger Global and Yamaha Motor Ventures, alongside D. E. Shaw Ventures and NAVER Ventures. The capital will support welding deployments, model development and expansion into additional manufacturing tasks and robotic forms.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
Path Robotics focuses on adaptive welding. The company says its Obsidian model uses sensor data to identify seams, plan welds and adjust execution as conditions change. These capabilities target variation in parts and heat distortion, but performance still requires assessment against specific materials, joint geometries, operating conditions and quality requirements.
The factory floor is becoming AI's next major arena. Even modest gains in throughput, quality, or efficiency ripple across entire industries. Successful deployments could generate revenue and useful operating experience. Whether deployment data improves shared models depends on data rights, quality, training and validated performance gains.
A $300 million round at a $2.45 billion valuation does more than fund operations—it signals that serious investors see something foundational taking shape. Industrial technology rarely attracts this excitement; factories are complex, sales cycles long, deployments difficult. When capital arrives at this scale anyway, it suggests investors anticipate a step-change in industrial economics.
The financing provides additional development resources, but a larger round does not establish stronger operating performance or lower execution risk. Still, funding is not validation. Valuation is an opinion formed at a moment in time, not proof of profitability or scalability. The real question is what the capital accomplishes: compute, model training, deployment, and expansion into new applications. Physical AI scales through data and field performance, not branding. Money accelerates those things but cannot shortcut them.
Path reports that annual recurring revenue grew 17-fold over the 18 months preceding the announcement. The release does not disclose starting or ending ARR or explain its calculation. The figure indicates company-reported commercial expansion, but does not establish recognised annual revenue, cash collection, retention or profitability.
That said, commercial traction in industrial markets is genuinely hard. Factories do not rewrite processes lightly. If growth is that fast, something is clearly resonating. What remains uncertain is the shape: broad adoption across many sites, or a handful of large contracts? Investors need absolute revenue figures, customer concentration, renewal rates, and margin structure before drawing firm conclusions. Growth captures attention; transparency earns conviction.
Welding provides an initial application for Path’s broader manufacturing ambitions. Operational data could inform subsequent model training, but improvements depend on data quality, permitted use, retraining and validation. More installations alone do not establish a compounding learning advantage.
Path plans to expand beyond welding into additional manufacturing tasks and robotic forms. Success in welding does not establish readiness for other processes, each of which brings different sensing, tooling, safety and quality requirements. Any move towards software-like margins must account for hardware, installation, maintenance, compute and field support costs.
The transition from product to platform is where visions are tested hardest. Physical environments are messy in ways digital ones are not. Broader ambition means greater execution burden. Deployment experience and proprietary data could support differentiation if they produce measurable gains in quality, reliability, deployment speed or customer economics relative to alternatives.
Excitement opens doors; industry demands evidence. The real scorecard is straightforward: does output rise, do defects fall, is uptime strong, and is total ownership cost attractive? Pilot projects are easy to celebrate and surprisingly hard to convert into scaled rollouts. Moving from trial to embedded production use is the more meaningful threshold.
Customer concentration, renewal rates, and expansion within existing accounts matter equally. Repeat adoption reveals more than any promotional claim because customers are spending based on lived experience. Economics matter too—fast revenue growth with weak margins or high service burdens does not resolve into a durable business.
Competitive pressure will intensify. Established robotics firms and AI-driven challengers are watching the same opportunity. Advantage depends on deployment speed, proprietary data, and the ability to turn technical capability into dependable industrial service.
The bottom line: Path Robotics’ financing and company-reported ARR growth support expansion of its adaptive-welding business. They do not establish fleet-wide performance, a durable learning advantage or profitable expansion into other manufacturing tasks. Investors should watch recognised revenue, collections, customer concentration, renewals, productive utilisation, weld quality and margins after hardware and field support.