Checkout.com’s U.S. Payments Surge and Fintech Infrastructure Expansion
– 3 min read
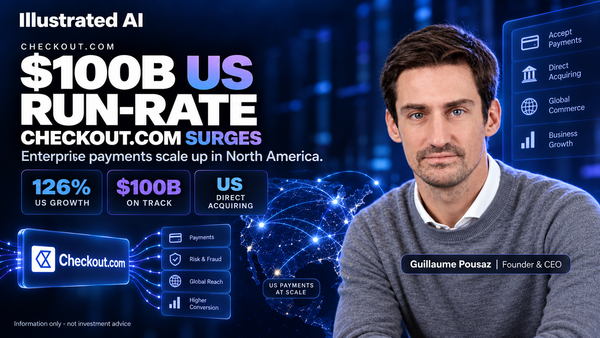
Checkout.com says its US payment volume increased 126% in the second quarter of 2026 compared with the same period in 2025. The company expects its US processing volume to exceed $100 billion by year-end, making the country its fastest-growing region.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
The United States is a highly competitive payments market. Checkout.com attributes its expansion to new enterprise customers and a greater share of payment volume from existing merchants. This indicates growing adoption, although payment volume does not by itself establish corresponding revenue growth or profitability. Payment performance can affect conversion, fraud losses, cash flow and international expansion, making payments infrastructure an important contributor to merchant economics.
Behind every smooth checkout sits dense technology making split-second decisions. Merchants now ask measurable questions: What is the approval rate? How quickly does a payment response return? How effectively does the system filter fraud without blocking good customers? At enterprise scale, even small improvements in authorization rates or latency can materially affect merchant revenue and customer conversion.
A provider woven into a merchant's commercial engine influences how subscriptions renew, how marketplaces split funds, and how cross-border commerce scales. That depth of integration can make payments infrastructure strategically important and increase switching costs, particularly when the provider’s performance directly affects merchant revenue.
Checkout.com says it is now one of only three companies processing US payments through a Merchant Acquirer Limited Purpose Bank structure. This gives the company direct access to card networks and reduces its reliance on an intermediary sponsor bank for acquiring. The structure may support greater control over payment performance, product development and operating economics.
For merchants, direct acquiring may support smoother onboarding, faster product development, greater control over the payment lifecycle and stronger payment performance. For investors, improved unit economics become possible as volume scales. Most significantly, it signals strategic ambition — a desire to own critical parts of the payment lifecycle and compete on architecture, not just interface design.
Beyond processing, a wider North American platform is taking shape across marketplaces, payouts, issuing, and regional expansion. Modern digital businesses need to collect funds, split payments, manage compliance, and send cross-border payouts — often simultaneously. An integrated stack handling all of this creates coherence rather than complexity.
Payouts make distributed business models possible. Issuing enables embedded finance and new revenue streams. Geographic expansion across San Francisco, Atlanta, New York, and a new Americas hub in Mexico builds local capability where payments knowledge genuinely matters. For investors, the attraction is share of wallet — a platform handling acquiring, payouts and issuing could capture a greater share of each customer’s payment activity and potentially support stronger retention.
Checkout.com did not announce an AI-agent payment product as part of this update. However, its infrastructure expansion is relevant to the broader development of increasingly automated and AI-enabled commerce. This creates new demands around identity verification, customer permissions, and fraud detection at machine speed — areas where providers controlling more of the payment lifecycle may be better positioned.
Competition remains intense but nuanced. Large merchants work with multiple providers, routing transactions based on geography and performance. The real opportunity is winning high-value workloads by demonstrating superior results — better approval rates, stronger resilience, smarter orchestration. Providers that demonstrate measurable performance advantages may earn a greater share of merchants’ payment flows over time.
Payments is evolving from mature utility into a fresh control layer for digital commerce. Competition is increasingly moving beyond basic payment processing toward the orchestration of identity, permissions, performance and money movement.
Growth attracts attention. Infrastructure depth determines durability.