Fal’s $16B Valuation Surge on AI Inference Demand
– 3 min read
Inference creates recurring computing demand as deployed AI models generate images, video and audio for users. Training and post-training remain important to model capability, while production inference brings its own requirements for speed, reliability and cost control. Fal operates across this production layer and also works on post-training generative media models.
Invest in top private AI companies before IPO, via a Swiss platform:
 SmartProfit Finder AG
Training is expensive but episodic. Inference is different. It becomes continuous, embedded into advertising, ecommerce, media production, and creator platforms. It stops being a laboratory activity and starts behaving like a utility. Investors are paying close attention to companies that make this possible, recognizing them as critical tollbooths in the digital economy. Intelligence without delivery is just potential. Delivery at scale is the business.
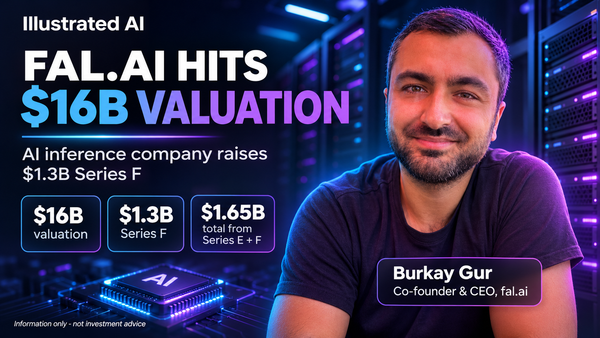
Founded in 2021 by Burkay Gur and Gorkem Yurtseven, fal provides infrastructure for running generative media models in production. It announced its Series E and F financings together on 3 November 2026, raising a combined $1.65 billion. Sequoia Capital led the Series E and Bessemer Venture Partners led the Series F, with NVIDIA participating as a strategic investor. Bloomberg reported that the $1.3 billion Series F closed in October at a $16 billion valuation, compared with $8 billion in April.
Bloomberg reported, citing a person familiar with the matter, that fal reached $800 million in annualised revenue earlier in 2026. This extrapolates a recent revenue pace; it is not equivalent to recognised annual revenue, contracted recurring revenue or profitability. The valuation jump signals that investors now view AI inference infrastructure, especially for media-heavy applications, as a category with serious revenue potential and strategic importance.
The company's core offering is not merely AI itself, but the production system around it. APIs and computing infrastructure allow developers and businesses to run generative media models at scale, turning novelty into workflow. A retailer generates product images in multiple styles. An advertiser creates campaign visuals rapidly. A gaming studio develops assets faster. Value is not the existence of the model. Value is dependable execution.
The best infrastructure providers improve scheduling, reduce idle time, and manage workloads intelligently, turning complex AI operations into a reliable utility. Integration into daily workflows could support retention, but switching costs depend on compatibility, pricing, service reliability and available alternatives. When AI stops being a trick and starts being work, the infrastructure behind it becomes incredibly valuable.
CEO Burkay Gur told Bloomberg that fal had to rate-limit customers during summer 2026 because it could not serve the demand. This is a company-reported capacity constraint, rather than a quantified backlog or evidence of profitable unmet demand. Service limitations can also affect customer satisfaction and retention.
Fresh capital can convert unmet interest into fulfilled revenue by procuring more GPUs and expanding infrastructure. But a bottleneck is only bullish if resolved intelligently. The key question is whether expanded supply translates into efficient, profitable usage, not just scale. The company that solves the bottleneck often earns strategic leverage. The opportunity is real. The next challenge is proving that scale can become profit.
Big valuations and fast growth create excitement, but proof comes after. Four areas deserve scrutiny:
The bottom line: fal’s financing and reported revenue momentum support expansion of its generative-media infrastructure business. They do not establish sustainable profitability or a durable competitive advantage. Investors should watch recognised revenue, customer retention and concentration, paid utilisation, service reliability and margins after compute, model licensing and support costs.